Renter to owner · The Last Lease
Before you renew, run the numbers.
A free, private rent-versus-own analysis for Denver renters. Your rent, your renewal and your numbers, written out on one page so the decision is yours to make with real information.
Sample
Rent vs. Own Ledger
Prepared for a Denver renter
Lease ends
June 2027
If you renew
- Rent today
- $3,800
- Year 2
- $3,876
- Year 3
- $3,954
- 3-year rent
- $139,554
- Equity built
- $0
If you own
- Monthly, all in
- In your Ledger
- Year 2
- In your Ledger
- Year 3
- In your Ledger
- Equity, year 3
- In your Ledger
- Crossover month
- In your Ledger
Taylor made our first-time home buying experience as smooth and efficient as possible! He truly advocated for us every step of the way and went above and beyond previewing homes for us. The home we decided to purchase was even Taylor's find! We could not have had a more knowledgeable or supportive realtor!
What three more leases actually cost.
Enter your rent and a renewal increase. This is rent only, with no equity on the other side. Your Ledger adds the ownership column, prepared with current lending figures.
Renewal offers usually arrive about 90 days before a lease ends, so until yours does, 2% is a reasonable placeholder. Some Denver buildings are offering incentives to stay right now, so enter your real number when you have it, even 0%.
Complete my LedgerRent paid over 36 months
$139,554
- Year 1
- $45,600
- Year 2
- $46,512
- Year 3
- $47,442
Your Ledger, in seconds.
One page. Both futures. Your Ledger is calculated the moment you submit, appears on your screen and arrives in your inbox. I then review every one personally and refine it with live lending figures.
Rent
Your next three years of rent
Built from your current rent and a realistic renewal increase.
Own
The monthly cost of owning, all in
Payment, taxes, insurance and HOA at the purchase price you choose.
Equity
What you would hold at years three and five
Principal paid down, shown plainly, with the assumptions written out.
Timing
The month owning overtakes renting
Sometimes it is now. Sometimes it is next year. Either way, you will know in writing.
Count back from your lease end.
The best time to start is about six months before your lease ends. Here is how the timing usually works, so your move lands on your schedule instead of your landlord's renewal deadline.
Phase 01 of 05
Six months before
Run your Ledger
See three more years of rent next to the real cost of owning, in writing, and decide whether this is the year.
Phase 02 of 05
Four to five months
Talk to a lender
A pre-qualification conversation, then pre-approval, so you know exactly what you can buy and your offers are taken seriously.
Phase 03 of 05
About three months
Start touring
A short list of homes worth your time. This is usually when your renewal offer arrives, and your lease notice requirement starts to matter.
Phase 04 of 05
About 60 days
Under contract
Inspections, appraisal and loan approval, usually 30 to 45 days from accepted offer to closing.
Phase 05 of 05
Lease end
Keys, then move
Close a few weeks before your lease ends so the move overlaps calmly instead of landing on one stressful weekend.
Your career shapes the plan. So does the loan.
Your Ledger is built with a trusted local lending partner, so the numbers you see are numbers you can act on. Pre-qualification does not affect your credit score.
Physician and hospital schedules
A plan that fits a call schedule, with physician loan options reviewed from the start.
Physician loans
Commission and variable income
How commission income is underwritten, and how to time a purchase around a strong year.
Commission income underwriting
Self-employed income
Ownership as part of the balance sheet, coordinated with your CPA and documented properly.
Self-employed income
New development and jumbo
Higher price points, new construction and private purchases, handled with discretion.
Jumbo and new development financing
10 or 15 percent down, no monthly mortgage insurance
Sunflower Bank’s Saver 90 and Saver 85 programs, through Pat Davis: the lender pays the mortgage insurance, so that line disappears from your payment.
Saver 90 and Saver 85
Salaried and W-2 income
A straightforward path for steady paychecks, with the loan type and down payment matched to your savings.
Conventional and FHA loans
Military and veterans
VA loan benefits, including options with no down payment, explained and coordinated from the first conversation.
VA loans
Buying with family help
Gift funds, co-borrowers and family contributions, documented the way your lender needs them.
Gift funds and co-borrowers
Lending partner: Pat Davis, Sunflower Bank · NMLS# 927485. Not a commitment to lend. All loans subject to approval. Equal Housing Lender.
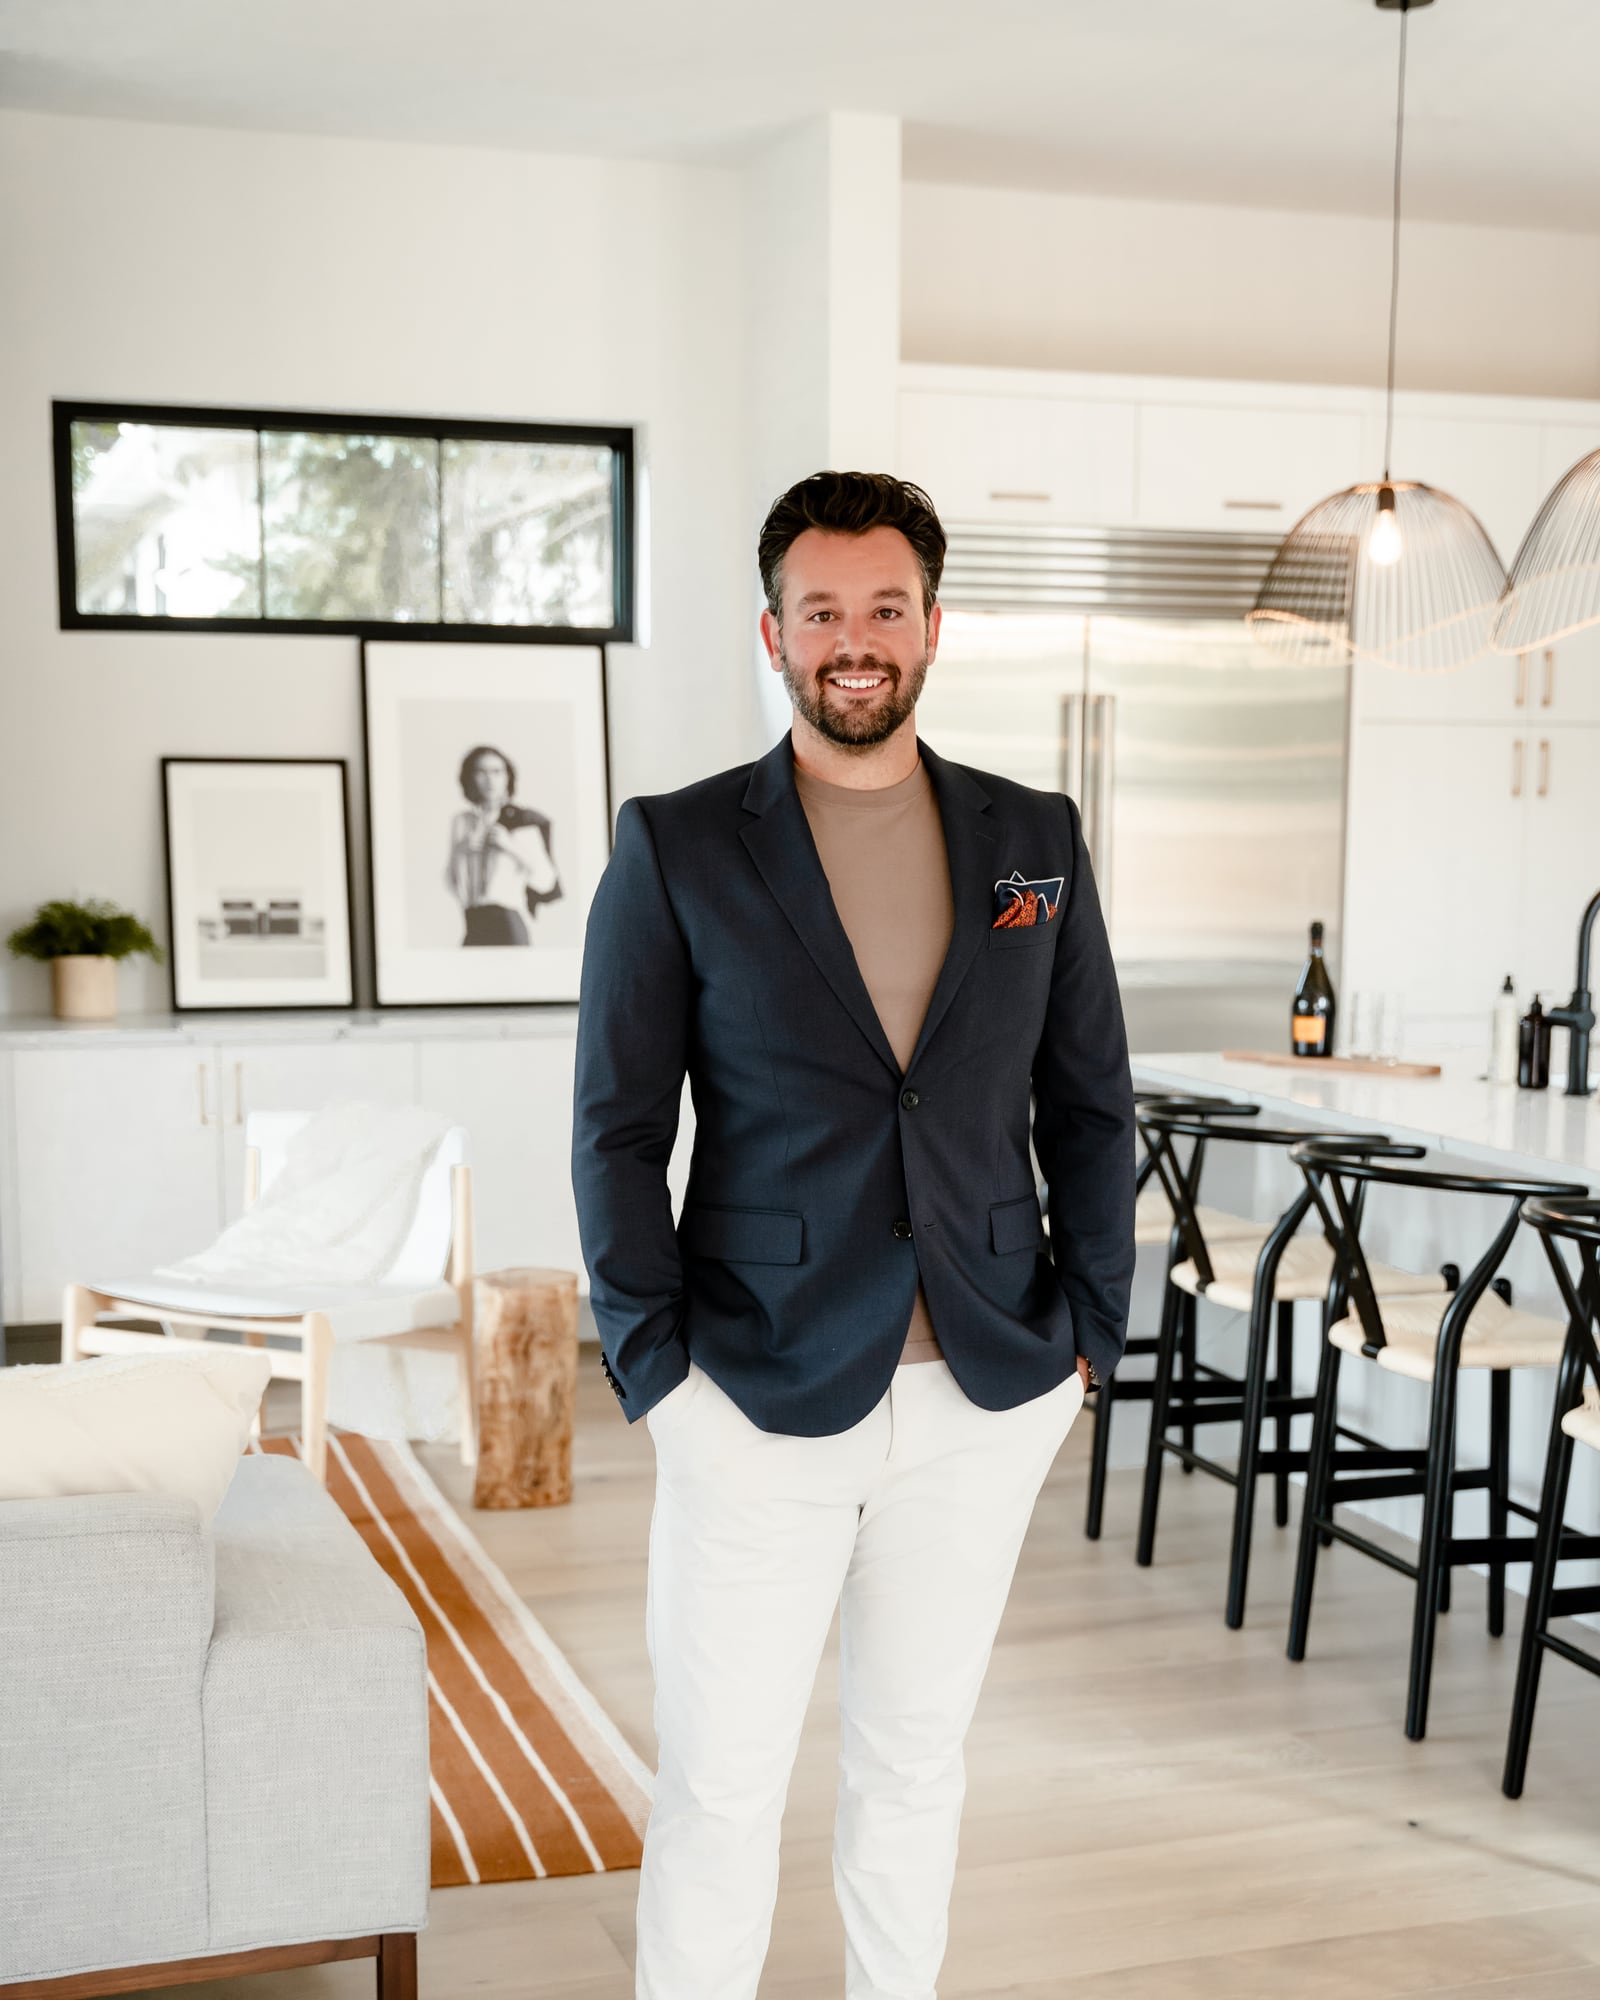
I have guided renters through this exact decision.
Many of my clients start exactly where you are: renting, weighing a renewal, and wondering whether buying makes sense yet. You receive the same process my luxury clients receive: access to new development, real negotiation and a calm plan from the first conversation to closing.
Buying now, buying next year and renewing with confidence are all good outcomes. My job is to make sure the choice is yours, made with real information.
A private table. A real conversation.
Coffee, a drink or dinner with me, for you and anyone who is part of the decision. No presentation and no pressure, just your numbers, the market and an honest conversation about whether this is your year.
What renters ask before they buy.
Straight answers to the questions I hear most. Anything else, call or text (352) 584-3411.
Can I buy before my lease ends?
Yes. Most renters aim to close a few weeks before the lease ends so there is time to move without paying for two places for long. If the right home appears earlier, many leases include an early termination option, and we can weigh that cost against the home in your Ledger.
What if I have to break my lease?
Start by reading your lease for an early termination clause or notice requirement, and talk to your landlord early. A known fee is often small next to the cost of missing the right home. This is general information, not legal advice; for your specific lease, ask your landlord or an attorney.
How much should I have saved?
Plan for your down payment plus closing costs of about 3 percent of the price, and keep a cushion after closing. Conventional loans can start at 3 to 5 percent down, and Sunflower Bank’s Saver 90 and Saver 85 programs through Pat Davis remove monthly mortgage insurance at 10 and 15 percent down.
Does checking my numbers affect my credit?
Requesting your Ledger does not involve a credit check. A pre-qualification conversation with a lender typically does not either. A full pre-approval usually does, and your lender will tell you before it happens.
How long does buying take?
Most purchases take two to four months from first conversation to keys: a few weeks to prepare, a search at your pace, and roughly 30 to 45 days under contract.
Is it ever better to keep renting?
Yes. Sometimes the numbers say renew this year and buy next year, and that is a good outcome. The Ledger shows the month owning overtakes renting so the decision is made on evidence, not pressure.
Make this your last lease.
Whether the answer is buy now, buy next year or renew with confidence, you will know in writing.